The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
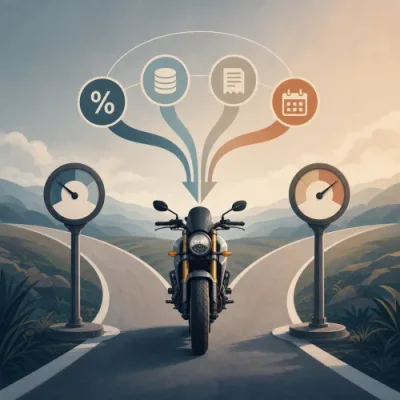
Motorbike loan interest rates affect your repayments, but they are only one part of the total finance cost. This guide explains how rates, comparison rates, fees, loan terms and borrower factors work in Australia.
Motorbike loan rates can make a noticeable difference to your repayments and the total amount you pay over the life of a loan. But the advertised interest rate is not the whole story. In Australia, borrowers comparing motorbike finance should also understand the comparison rate, loan fees, repayment structure and the lender's assessment criteria before applying.
This guide explains what affects motorcycle loan interest rates, how comparison rates work, the difference between fixed and variable rates, and how to compare finance costs without focusing on one number alone. It is general information only and does not take your personal objectives, financial situation or needs into account.
What is a motorbike loan interest rate?
A motorbike loan interest rate is the rate a lender charges on the amount you borrow. It helps determine how much interest you pay in addition to repaying the original loan amount.
For example, if two loans have the same loan amount and term but different interest rates, the loan with the higher interest rate will usually have higher repayments and a higher total interest cost, assuming all other loan features and fees are the same.
In practice, all other features are rarely identical. Fees, loan term, repayment frequency, secured or unsecured structure, early repayment rules and other conditions can all change the real cost of motorcycle finance.
What affects motorbike loan rates in Australia?
Motorcycle loan interest rates are usually shaped by a mix of lender policy, borrower profile and loan details. Lenders assess applications differently, so the same borrower may receive different quotes from different providers.
Your credit history and credit score
Your credit profile can influence both eligibility and pricing. A lender may consider your repayment history, existing credit accounts, defaults or arrears, recent credit enquiries and overall credit conduct. A stronger credit profile may support access to more competitive options, but outcomes depend on the lender's criteria.
Your income, employment and repayment capacity
Lenders generally want to understand whether the proposed repayments are affordable. They may review income, employment stability, regular expenses, existing debts and other financial commitments. A stable income does not guarantee approval, but it can form part of the lender's assessment.
The loan amount and deposit
The amount you borrow affects both repayments and risk. A larger loan usually means higher repayments and more interest paid over time. Paying a deposit or reducing the amount borrowed may reduce the total finance cost, although the effect depends on the rate, term and fees.
The motorcycle being financed
For secured motorcycle loans, the bike itself may be part of the assessment. Lenders may consider whether the motorcycle is new or used, its age, value, condition, make, model and whether it meets their security requirements. Some lenders may apply different criteria to older, imported, modified or private-sale motorcycles.
Secured versus unsecured loan structure
A secured motorcycle loan uses the bike as security for the loan. Because the lender has collateral, secured loans may sometimes be priced differently from unsecured loans. An unsecured loan does not use the motorcycle as security, which may lead to different rates, borrowing limits or eligibility criteria.
The cheaper-looking option is not always the better option for every borrower. Secured loans can involve asset-related conditions and repossession risk if repayments are not made. Unsecured loans may offer simpler asset requirements but can have different pricing and borrowing limits. If you want a deeper comparison of these structures, see secured versus unsecured motorcycle loans.
The loan term
The loan term is the period over which you repay the loan. A longer term can reduce each scheduled repayment, but it may increase the total interest paid because the debt is outstanding for longer. A shorter term can increase repayments but may reduce total interest, assuming the rate and fees are otherwise similar.
Before applying, it can help to test different terms and repayment amounts using a bike loan calculator. Calculator results are estimates only and will not confirm eligibility, approval or the final cost of a lender's offer.
Fees and loan features
Some loans include establishment fees, monthly or annual fees, broker fees, early repayment fees, late payment fees or other charges. The names and amounts vary by provider. Flexible features, such as additional repayments or redraw, may also come with conditions.
Fees can change the true cost of a loan, especially when comparing two offers with similar interest rates. Always review the credit contract and fee schedule before signing.
Interest rate versus comparison rate
The interest rate tells you the rate charged on the loan balance. The comparison rate is designed to help show the cost of the loan by combining the interest rate with certain standard fees and charges into a single annual percentage figure.
In simple terms, the comparison rate may help you compare loan offers more fairly than using the advertised interest rate alone. However, it is not a personalised quote and it may not reflect the exact cost of your proposed loan.
| Rate type | What it shows | What to watch |
|---|
| Interest rate | The rate charged on the loan balance. | It does not show all fees or the full cost of the loan. |
| Comparison rate | An annual percentage figure that includes the interest rate and certain standard fees. | It is based on assumptions and may not include every cost or reflect your exact loan amount and term. |
What comparison rates do and do not include
A comparison rate can be useful, but it has limits. It usually includes the interest rate plus certain known fees and charges that apply to the loan. It may not include costs that depend on your behaviour, optional choices or circumstances.
Costs that may not be reflected in a comparison rate can include:
- government charges or registration-related costs;
- insurance premiums;
- late payment fees;
- break costs or early repayment charges where applicable;
- optional add-ons or protection products;
- fees that only apply in certain situations; and
- costs connected with changing or varying the loan later.
The comparison rate is also based on a representative loan scenario. If your loan amount, term, repayment frequency or fee structure differs, your actual cost may differ from the advertised comparison rate.
Why a lower interest rate may not mean a cheaper loan
It is possible for a loan with a lower advertised interest rate to cost more overall than another loan with a higher rate. This can happen if the lower-rate loan has higher fees, a longer term, less flexible repayment options or charges that apply when you repay early.
When comparing motorcycle loan interest rates, look at:
- total repayments: how much you expect to repay over the full term;
- upfront and ongoing fees: establishment, account keeping and other charges;
- repayment frequency: weekly, fortnightly or monthly repayments may affect budgeting;
- loan term: shorter and longer terms can change the total interest cost;
- early repayment rules: whether extra repayments are allowed and whether fees apply;
- security conditions: whether the bike is used as collateral; and
- balloon or residual payments: whether a larger amount is due at the end of the loan.
Fixed rate motorcycle loans
A fixed rate motorcycle loan has an interest rate that stays the same for an agreed period, often for the full loan term. This can make repayments more predictable, which may help with budgeting.
Potential advantages of a fixed rate include:
- clearer repayment expectations;
- protection from rate increases during the fixed period; and
- simpler budgeting for regular repayments.
Potential limitations can include:
- less flexibility to make extra repayments;
- fees or restrictions for early repayment; and
- no benefit if market rates fall, unless refinancing is available and worthwhile.
Fixed rates may suit borrowers who value repayment certainty, but whether they are appropriate depends on the loan conditions and the borrower's circumstances.
Variable rate motorcycle loans
A variable rate motorcycle loan has an interest rate that can change during the loan term. If the rate changes, your repayments or total interest cost may also change.
Potential advantages of a variable rate include:
- possible access to more flexible repayment features;
- potential benefit if rates decrease; and
- fewer early repayment restrictions in some loan products.
Potential limitations can include:
- less repayment certainty;
- higher repayments if rates increase; and
- the need to maintain a budget buffer for rate movement.
Variable rates can be useful for some riders, but they require comfort with repayment changes and careful checking of the loan terms.
How loan term changes the total cost
The loan term can be just as important as the rate. A longer term may make repayments look more manageable month to month, but it can increase the amount of interest paid over time. A shorter term may reduce total interest, but the higher repayments need to fit comfortably within your budget.
When reviewing a quote, ask the lender or broker to show:
- the repayment amount;
- the total amount payable over the term;
- the total interest payable;
- all upfront and ongoing fees;
- whether extra repayments are allowed; and
- what happens if you repay early or refinance.
This helps you compare the total cost of bike financing rather than only comparing the headline rate.
How fees can affect motorbike finance costs
Fees can be easy to overlook when a rate looks competitive. Even a modest ongoing fee can add to the total cost over several years, while upfront fees can affect the amount you need to pay at settlement or add to the amount financed.
Common fee categories to check include:
- application or establishment fees: charged when the loan is set up;
- monthly or annual account fees: charged during the loan term;
- broker or introducer fees: where a third party assists with the finance process;
- late payment fees: charged if repayments are missed or delayed;
- early repayment fees: charged by some lenders if you repay ahead of schedule; and
- variation fees: charged if you change loan terms later.
Not every loan includes every fee. The key is to compare the fees that apply to your actual quote and to read the loan agreement carefully. For contract review points, see what to look for in a motorcycle loan agreement.
Risk-based pricing and personalised rates
Many motorbike loan rates are personalised. This means the rate you see advertised may not be the rate you are offered after assessment. A lender may price the loan based on credit risk, repayment capacity, loan amount, loan term, security value and other policy factors.
This is why two riders seeking similar motorcycle finance may receive different rates. It is also why an advertised rate should be treated as a starting point for comparison rather than a confirmed outcome.
Before submitting multiple applications, consider whether the provider can give an indicative quote or pre-assessment and whether it involves a credit enquiry. Credit enquiry practices vary, and multiple formal applications may affect your credit report.
Questions to ask before accepting a motorcycle loan rate
When you receive a finance quote, these questions can help you understand the real cost:
- Is the rate fixed or variable?
- What is the comparison rate and what assumptions is it based on?
- What fees are included and excluded?
- What is the total amount payable over the loan term?
- Can I make extra repayments without penalty?
- Are there early payout or break costs?
- Is the loan secured against the motorcycle?
- Are there insurance or usage conditions?
- Does the repayment amount include any balloon or residual payment structure?
- What happens if I miss a repayment or experience financial difficulty?
How to compare motorbike loan rates responsibly
A responsible comparison considers both cost and suitability. A low repayment may look attractive, but it could be caused by a long loan term or a final balloon payment. A low advertised rate may not include fees. A flexible loan may cost more but offer features that matter to your repayment plans.
A practical comparison process is to:
- Set a realistic bike budget, including gear, insurance, registration, maintenance and running costs.
- Estimate repayments across different loan terms.
- Compare interest rates and comparison rates together.
- List all upfront, ongoing and conditional fees.
- Check secured versus unsecured conditions.
- Review early repayment and default clauses.
- Read the credit contract before signing.
The goal is not simply to find the lowest advertised rate. It is to understand the cost, conditions and risks of the loan you are considering.
Bottom line
Motorbike loan interest rates are important, but they are only one part of motorcycle finance costs. The comparison rate can provide a broader view by including certain fees, but it is still based on assumptions and may not match your exact loan scenario.
Before applying, compare the interest rate, comparison rate, fees, loan term, repayment flexibility, security requirements and total amount payable. Your final rate, eligibility and loan conditions will depend on your individual circumstances and the lender's criteria.
Published: Friday, 7th Aug 2026
Author: Paige Estritori


I nearly got caught by a low repayment with a balloon at the end, so checking total payable really matters.