Bike Loans Australia Bike Loan Repayment Calculator
Calculate motorcycle loan repayments in seconds with our Bike Loan Calculator. Compare finance options and plan your ride with confidence.
Calculator results are estimates based on the inputs and assumptions used and are for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
Bike Loan Details:
Important!
Bike Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Bike Loan Amortisation Calculator
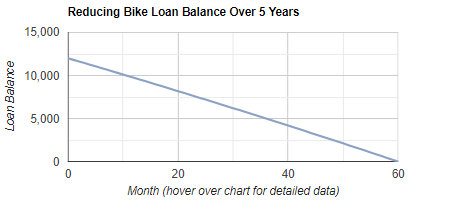
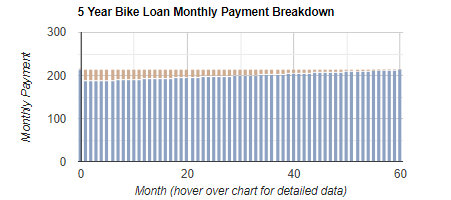
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Bike Loan Repayment Calculator
Our Bike Loan Repayment Calculator is designed to estimate your motorcycle loan repayments in seconds, so you can compare bike finance options and plan your budget before you commit. It is important because small changes to loan size, term length and interest rate can materially change your monthly repayment and the total interest you pay over the life of the loan.
This calculator provides estimates only and is not personal financial advice. Results do not take into account your objectives, financial situation or needs. Interest rates and fees vary by lender and your individual circumstances, and your final rate can only be confirmed after an application is assessed.
How to complete the form for the best result:
1. Purchase Price
Enter the bike purchase price as a whole number (no dots or commas). If you expect to borrow extra for on-road costs such as stamp duty, registration or insurance, include those amounts in the figure you enter so the estimate better reflects your likely loan amount.
2. Deposit or Trade-in Value (if applicable)
Enter your deposit or trade-in value as a whole number. If you have no deposit, enter 0. A higher deposit generally reduces the amount borrowed and can reduce interest paid over time.
3. Term of Loan (Years)
Select a term between 1 and 7 years. Longer terms typically reduce monthly repayments but can increase the overall cost of the loan due to more interest over time. Choose a term that fits your cash flow, not just the lowest repayment.
4. Interest Rate (% per annum)
Select an interest rate for the simulation. If you are unsure, test a conservative higher rate to see whether repayments remain affordable.
5. Calculate
Click calculate to generate your estimated repayment and amortisation visuals.
How to interpret the results:
1. Repayment estimate
Use the repayment figure as a starting point for budgeting, then stress-test by increasing the rate or reducing your deposit to see how sensitive repayments are.
2. Amortisation graphs
Review the loan balance chart to understand how quickly you reduce what you owe, and the interest versus principal chart to see how much of each repayment goes to interest compared with reducing the loan balance over time.
Motorcycle loan applicants in Australia should understand how responsible lending, credit contracts, hardship support, credit reporting and complaints processes can affect them before and after signing a loan agreement. - read more
Motorbike loan interest rates affect your repayments, but they are only one part of the total finance cost. This guide explains how rates, comparison rates, fees, loan terms and borrower factors work in Australia. - read more
A credit score is a numerical representation of an individual's creditworthiness based on their financial history, payment habits, and level of existing debt. It plays a crucial role in determining loan eligibility and interest rates for various financing options, including motorcycle loans. - read more
Balloon payments, deposits and trade-ins can change both the monthly repayments and the total cost of a motorcycle loan. This guide explains how these loan structure choices work in Australia, what to check before signing, and how to compare repayment scenarios with clearer expectations. - read more
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85 per cent gives Australian motorcycle buyers a fresh reason to slow down and test their numbers before committing to a new or used bike. The move follows stronger inflation readings, including September annual CPI of 4.3 per cent and trimmed mean inflation of 3. - read more
Australia’s motorcycle market is ahead of last year after the first nine months of 2026, but the latest FCAI-audited figures point to a recovery driven mainly by off-road demand rather than a uniform lift across every type of bike. For riders thinking about motorbike finance, that distinction matters because the practical costs attached to a trail bike, junior motorcycle, scooter or road machine can look very different once purchase price, transport, gear, insurance and maintenance are considered together. - read more
The latest national lending indicators give motorcycle buyers another useful signal: Australians are still willing to finance vehicles, but the decision is increasingly being shaped by repayment comfort rather than headline purchase price alone. - read more
Fresh September personal loan comparisons are a useful checkpoint for Australian riders planning to finance a new or used motorcycle. While headline interest rates remain an obvious starting point, the latest market settings continue to show why borrowers should look beyond the most attractive advertised number before making a decision. - read more