The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
A motorcycle loan can help spread the cost of a new or used bike, but it also creates a repayment commitment that should fit comfortably with your broader finances. Before borrowing for your dream motorcycle, consider the full cost of ownership, how different loans work, and what lenders may assess during the application process.
Before you borrow: what a motorcycle loan really involves
A motorcycle loan is a finance product used to purchase a new or used motorbike. If approved, the lender provides funds for the purchase and you repay the amount borrowed, plus interest and any applicable fees, over an agreed loan term.
Motorcycle finance can make a bike purchase more manageable by spreading the cost over time, but it also means the bike may cost more overall than its purchase price. The right decision is not just about whether you can meet the monthly repayment; it is also about understanding the total loan cost, ownership costs and the obligations in the loan contract.
Here are five practical areas to review before taking out a loan for your dream motorcycle.
1. Check your budget and borrowing capacity
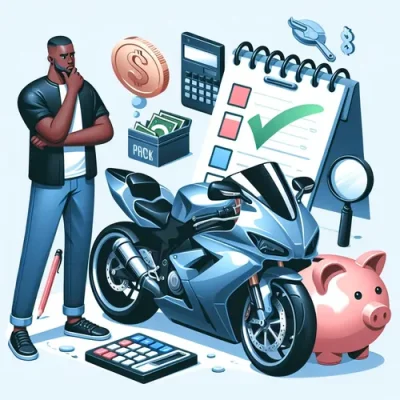
Start with your current financial position. List your regular income and subtract your existing expenses, debt repayments and savings commitments. The amount left over can help you estimate what may be available for motorcycle loan repayments without placing pressure on essential costs.
When reviewing affordability, allow for more than the advertised repayment. A realistic motorcycle budget may include:
- loan repayments, including interest and fees;
- registration and insurance costs;
- fuel;
- servicing, maintenance and repairs;
- riding gear and accessories;
- possible modifications or immediate upgrades; and
- a buffer for unexpected expenses.
Online calculators can help you test different loan amounts, rates and terms. For example, a personal loan repayment calculator can be useful when estimating how the loan amount and term may affect repayments.
Think beyond the monthly repayment
A longer loan term may reduce the repayment amount, but it can also increase the total interest paid over the life of the loan. A shorter term may cost more each month but may reduce the overall borrowing cost. The aim is to find a repayment structure that fits your budget while keeping the total cost of the loan in view.
Review your credit position
Your credit score and credit history can influence whether a lender is willing to offer finance and the terms that may be available. A stronger credit profile may support access to more favourable loan conditions, while a weaker profile may lead to higher costs or more limited options.
Before applying, consider checking your credit report and reviewing it for errors. Paying down existing debts and avoiding multiple unnecessary credit applications may also help present a clearer financial picture to lenders.
2. Understand the type of motorcycle loan
Motorcycle loans can be structured in different ways. Two common categories are secured and unsecured loans.
| Loan type | How it generally works | Points to consider |
|---|
| Secured motorcycle loan | The motorcycle is used as security for the loan. | The lender may be able to repossess the bike if repayments are not made. Secured loans may have different rates or conditions because the lender has security over the asset. |
| Unsecured loan | No motorcycle is used as loan security. | The lender takes on more risk, so interest rates may be higher. Eligibility and loan terms can vary between lenders. |
Different lenders may also offer different repayment frequencies, loan terms, fees and flexibility. Some loans may allow extra repayments or early payout, while others may charge fees for doing so. If you are comparing loan structures, it may help to read more about motorbike loan interest rates and comparison rates so you understand how headline rates and total costs can differ.
Read the contract terms carefully
Before signing a loan agreement, check the details of the repayment schedule, interest rate, fees, early repayment rules and what happens if you miss a payment. Also consider whether you can sell the motorcycle before the loan is repaid and what steps would be required if the loan is secured against the bike.
If you decide to compare available finance options, keep the focus on the total cost and contract terms rather than only the advertised repayment. You can also compare motorcycle finance options as part of your research before making an application.
3. Choose a motorcycle that fits your finances and riding plans
The motorcycle itself has a direct effect on your loan. A more expensive bike generally means a larger loan amount, higher repayments and potentially more interest over time. It can also affect insurance, maintenance and repair costs.
Think about how you plan to use the bike. A daily commuter, weekend cruiser, sports bike and long-distance tourer may each have different running costs, comfort factors, servicing needs and resale considerations.
New versus used motorcycles
A new motorcycle may offer the latest features, warranty coverage and the reassurance that it has not had previous wear and tear. However, it usually comes with a higher purchase price and may depreciate quickly after purchase.
A used motorcycle may cost less upfront, but finance terms, condition, servicing history and repair costs need careful review. If you are weighing up both options, this guide to new vs used motorcycles in Australia explores the finance considerations in more detail.
Depreciation and loan balance
Motorcycles can lose value over time. If the bike's market value falls below the remaining loan balance, you may owe more than the motorcycle is worth. This can matter if you want to sell or trade in the bike before the loan is repaid, because you may need to cover any shortfall.
4. Compare lenders, rates, fees and flexibility
Loan offers can vary between banks, credit unions, dealerships and other lenders. The interest rate is important, but it is only one part of the cost. When comparing loan options, review:
- the interest rate and whether it is fixed or variable;
- the loan term;
- application, establishment or processing fees;
- ongoing account fees;
- late payment fees;
- early repayment or exit fees;
- whether extra repayments are allowed;
- the repayment frequency; and
- any conditions attached to promotional offers.
Introductory offers, cashback-style promotions or first-time buyer programs may appear attractive, but it is important to understand what happens after any promotional period ends and whether the standard terms still suit your situation.
Loan flexibility can matter later
Your circumstances may change during the loan term. A loan that allows extra repayments, early payout or some repayment flexibility may be helpful if your income, expenses or priorities change. On the other hand, rigid terms or penalties may limit your options.
5. Prepare for the application process
Lenders generally assess your ability to repay the loan before making a decision. The exact process varies, but you may be asked to provide information and documents such as:
- personal identification, such as a driver licence or passport;
- proof of income, such as payslips or tax information;
- details of employment or business income;
- proof of address;
- information about existing loans, credit cards and other debts;
- details of living expenses; and
- information about the motorcycle being purchased.
The lender may also conduct a credit check and review your income, debts and expenses. Some lenders may provide a quick preliminary response, while others may take longer to complete a detailed assessment.
Common pitfalls to avoid
Before applying, watch for mistakes that can make a motorcycle loan harder to manage:
- Borrowing more than needed: financing extras or upgrading beyond your budget can increase repayments and total interest.
- Ignoring ownership costs: insurance, maintenance, repairs, fuel and gear can materially affect affordability.
- Focusing only on the repayment: a low repayment may be linked to a longer term and higher total interest.
- Skipping the fine print: fees, early repayment rules and default consequences can affect the real cost of the loan.
- Applying before checking your finances: reviewing your credit report, debts and budget first can help you understand your position before making an application.
Final thoughts
Taking out a motorcycle loan is a significant financial commitment. Before borrowing, assess your budget, understand the loan type, choose a bike that suits both your riding goals and finances, compare loan terms carefully and prepare the documents a lender may request.
A dream motorcycle should fit within a sustainable ownership plan. By considering the full cost of the bike, the loan and the ongoing expenses, you can approach motorcycle finance with clearer expectations and fewer surprises.
Published: Wednesday, 28th Aug 2024
Author: Paige Estritori




No comments yet. Be the first to share your thoughts.