Bike Loans Australia Personal Loan Repayment Calculator
Explore potential personal loan repayment scenarios with our Personal Loan Calculator. Test different borrowing amounts, interest rates and loan terms, and review estimated repayment schedules to see how varying assumptions may affect your repayments and total borrowing costs.
Calculator results are estimates based on the inputs and assumptions used and are for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations, and do not indicate that a lender will provide credit. Actual repayments and costs may differ.
Personal Loan Details:
Important!
Personal Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Personal Loan Amortisation Calculator
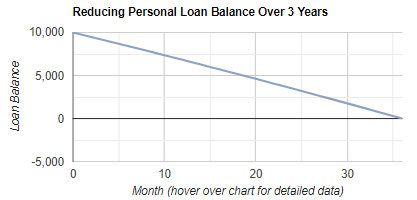
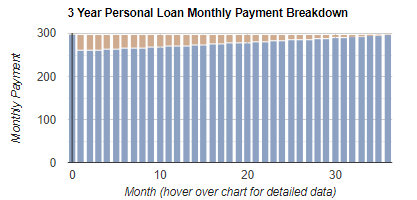
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Personal Loan Repayment Calculator
Our Personal Loan Repayment Calculator helps you estimate your ongoing loan repayments and the total cost of borrowing before you apply. By adjusting the loan amount, loan term and interest rate, you can compare scenarios and choose a repayment level that better fits your budget. It also provides an amortisation view so you can see how each repayment is split between interest and principal over time.
Important note for ASIC compliance: this calculator provides general information only and does not take into account your objectives, financial situation or needs. Results are estimates and may not include lender fees, comparison rates, commissions, insurance, redraw features, or changes to your interest rate. Always check a lender’s final quote and loan contract before deciding.
How to complete the form for the best result
1. Loan Amount Required: Enter the total amount you want to borrow in Australian dollars as a whole number (no decimals or commas). Use the amount you actually need, not the maximum you might be approved for, to avoid overpaying interest.
2. Term of Loan: Select the number of years you plan to repay the loan over. A longer term can reduce the monthly repayment, but typically increases the total interest paid over the life of the loan.
3. Interest Rate: Choose an annual interest rate for the simulation. If you have a lender quote, use that rate. If not, test a conservative range to understand best case and worst case outcomes.
4. Calculate: Click the calculate button to generate your results.
How to interpret the results
1. Repayment estimate: Treat the repayment figure as your baseline commitment. Stress-test your budget by increasing the rate or shortening the term to see if repayments remain affordable.
2. Amortisation and graphs: Review the month-by-month amortisation view and charts to understand how the balance reduces and how early repayments often include a higher interest portion, shifting toward more principal over time.
3. Compare scenarios: Re-run the calculator with different terms and rates to balance affordability (cash flow) against total interest (overall cost).
For motorcycle enthusiasts, owning and maintaining a bike is not just a hobby; it's a way of life. However, the financial aspects of this passion can sometimes be overwhelming. That's where budgeting comes into play. - read more
Feeling the wind rushing past you as you glide down the open road, with the growl of the engine as your soundtrack – the thrill of motorcycle ownership is a unique blend of freedom, excitement, and passion. In Australia, where the vistas are as captivating as the sense of adventure, owning a motorcycle is not just about transportation; it's a way to experience the landscape to its fullest. - read more
Financing a used motorcycle can be practical, but it adds extra checks around ownership, existing finance, condition, registration and loan settlement. This guide explains the key steps Australian buyers should take before committing. - read more
Buying a motorcycle can be exciting, but applying for finance is easier to approach when you understand your budget, documents, credit position and ownership costs first. This guide explains the key steps to take before applying for a motorcycle loan in Australia, so you can compare options with clearer expectations and avoid rushing into a commitment you have not fully reviewed. - read more
Australia’s motorcycle market is ahead of last year after the first nine months of 2026, but the latest FCAI-audited figures point to a recovery driven mainly by off-road demand rather than a uniform lift across every type of bike. For riders thinking about motorbike finance, that distinction matters because the practical costs attached to a trail bike, junior motorcycle, scooter or road machine can look very different once purchase price, transport, gear, insurance and maintenance are considered together. - read more
The latest national lending indicators give motorcycle buyers another useful signal: Australians are still willing to finance vehicles, but the decision is increasingly being shaped by repayment comfort rather than headline purchase price alone. - read more
Fresh September personal loan comparisons are a useful checkpoint for Australian riders planning to finance a new or used motorcycle. While headline interest rates remain an obvious starting point, the latest market settings continue to show why borrowers should look beyond the most attractive advertised number before making a decision. - read more
Fresh national economic figures have given Australian borrowers another reason to stay practical when planning a motorcycle purchase. While the latest growth signals suggest the economy is still moving forward, they also reinforce a familiar message for riders: finance conditions can remain uneven even when broader market confidence improves. - read more
Private Mortgage Insurance (PMI): A type of insurance that a borrower might be required to purchase as a condition of a conventional mortgage loan, if the down payment is less than 20% of the property value.