Bike Loans Australia :: Articles

The Truth Behind Payday Loans

What should you know about the reality of payday loans?

The Truth Behind Payday Loans

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

There’s a lot been said about payday loans. Many claim that the interest rates charged are outrageous. Others say that they are the only source of finance available for those with less than perfect credit score. There is a bit of truth in both claims but there is much more to payday loans than meets the eyes.

A Simple Concept

When Pay Day Loans first appeared in the finance industry, they came to fill a gap not covered by any other financial product.

The original idea which remains in most of the loan products of this kind is to provide a small amount of money, usually up to half of the borrower’s wage for a short term (till pay day) at the end of which the money is reimbursed plus a fee or an amount of interests.

This was a simple and speedy way to solve a temporary lack of funds.

Traditional personal loans took too much time to be approved because there were too many credit examinations to be done.

The whole concept was extremely simple: A small amount, a short term, fast approval.

How do lenders get a return on such small amounts?

Even simpler, the interest rate charged is considerably higher. The high return in terms of percentages also came to justify the high risk involved in these transactions for the lender.

Since there are no credit checks whatsoever and the loan is unsecured, there is absolutely no guarantee that the borrower is going to return the money (other than his/her salary).

The Actual Situation

Problems began when the proliferation of this kind of loan drew so many unscrupulous lenders to this new market.

In order to attract new customers they began to offer longer repayment programs, loan renovations, interest reschedules, etc.

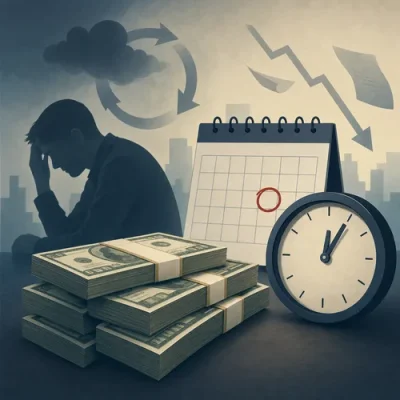
As with credit cards the flexibility offered by Pay Day Loan lenders began to create a vicious circle for many people that had no control over their finances.

Bike Loans Australia Motorcycle News Insights
Podcast Cover Image Weekly wrap for 21 November 2026: RBA minutes point to a split vote on the early?November cash?rate rise while markets now expect no further hikes and possible cuts next year. ZXMOTO launches locally with sharp ride?away pricing and December deliveries. Black Friday “fake postie” scams spike; protect your banking and ID. NSW police charge four over an alleged multi?million?dollar motor claims scam, a reminder to keep insurance settings and records in order. Practical takeaways focus on budgeting with comparison rates, total on?road costs, and safer online habits before applying for finance.

Thus, they take a pay Pay Day Loan, fail to repay it on time and take another one in order to pay the previous one and so on.

Debt starts accumulating, interests increase and sooner or later a debt consolidation program is necessary or worst, they have to file for bankruptcy.

It’s as unfair to say that the whole responsibility belongs to the lenders as it is to say they have no responsibility at all.

The advertisements, the hidden loan terms concealed in the fine print of loan contracts too long for anyone in a desperate situation to read and the easiness with which some lenders extend loans for people they know can’t repay without making huge sacrifices has a lot to do with the bad reputation of Pay Day Loans.

Applying for a Pay Day Loan is not a sin

If an unexpected situation arises and you don’t have the money you need to solve it, nor you have the time to resort to other forms of finance and you know that you’ll be able to repay the loan without problems by next payday, it won’t kill you to request a Pay Day Loan.

What you need to understand is that they are meant for emergency situations and you must avoid taking it as a habit to request a Pay Day Loan every time you need extra cash for whatever reason.

Published: Tuesday, 24th Aug 2021
Author: 11
Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Bike Loans Articles

Financing Your First Motorcycle: Tips for Australian Riders
Securing a motorcycle loan is a significant step for many Australians who dream of hitting the open road on two wheels. Not only does it provide personal freedom, but it also offers a sense of adventure and independence that’s hard to match. - read more
How Balloon Payments, Deposits and Trade-Ins Affect Motorcycle Loans
Balloon payments, deposits and trade-ins can change both the monthly repayments and the total cost of a motorcycle loan. This guide explains how these loan structure choices work in Australia, what to check before signing, and how to compare repayment scenarios with clearer expectations. - read more
What to Look for in a Motorcycle Loan Agreement
Before signing a motorcycle loan agreement, it is worth understanding exactly how the loan works, what it may cost and what obligations you are accepting. This guide explains the key clauses, repayment details, fees and lender terms Australian riders should review before committing. - read more
What Lenders Look For: Insights to Enhance Your Bike Financing Eligibility
Thinking about buying a motorbike? Whether you're upgrading your current ride or diving into the world of motorbiking for the first time, securing the right finance is crucial. In Australia, bike loans can open the door to owning your dream motorbike, but the application process holds its share of challenges. - read more

Finance News

Fresh November Loan Rates Sharpen the Bike Budget Test
18 Nov 2026: Paige Estritori
Australian riders planning a financed motorcycle purchase have a fresh November benchmark to consider, with Canstar’s latest personal loan data showing low advertised rates remain available in parts of the market, but not necessarily to every borrower or every loan structure. - read more
Road Vehicle Finance Edges Higher in a Cooler Lending Market
11 Nov 2026: Paige Estritori
Fresh September quarter lending data points to a more cautious Australian credit market, but road vehicle finance has not moved in a straight line with the broader slowdown. For riders considering motorbike finance, the latest figures are useful because they show continued borrowing activity for vehicles even as households face tighter rates, softer housing lending and more pressure on discretionary budgets. - read more
Rate Rise Gives Riders a Fresh Budget Check
04 Nov 2026: Paige Estritori
The Reserve Bank of Australia’s 3 November 2026 decision to lift the cash rate target by 25 basis points to 4.85 per cent gives Australian motorcycle buyers a fresh reason to slow down and test their numbers before committing to a new or used bike. The move follows stronger inflation readings, including September annual CPI of 4.3 per cent and trimmed mean inflation of 3. - read more
Off-Road Boom Changes the Motorcycle Budget Conversation
28 Oct 2026: Paige Estritori
Australia’s motorcycle market is ahead of last year after the first nine months of 2026, but the latest FCAI-audited figures point to a recovery driven mainly by off-road demand rather than a uniform lift across every type of bike. For riders thinking about motorbike finance, that distinction matters because the practical costs attached to a trail bike, junior motorcycle, scooter or road machine can look very different once purchase price, transport, gear, insurance and maintenance are considered together. - read more

Knowledgebase
Working Capital:
A measure of a company's short-term financial health, calculated as current assets minus current liabilities.